

If you’re thinking about buying a home, there’s one step I always encourage before you start touring: getting pre-approved. It isn’t the most glamorous part of the process, but it’s one of the most helpful. Here’s what it is, how it works and why it matters, especially here in Lamorinda.
What is a pre-approval?
A pre-approval is a letter from a lender saying how much they’re willing to lend you, based on a review of your finances. The lender looks at your income, debts, savings and credit, then tells you what you’re likely to be able to borrow.
Think of it as a trusted, informed estimate of your budget, backed by real documents. It turns “I think I can afford this” into “I know where I stand.”
Pre-approval vs. pre-qualification
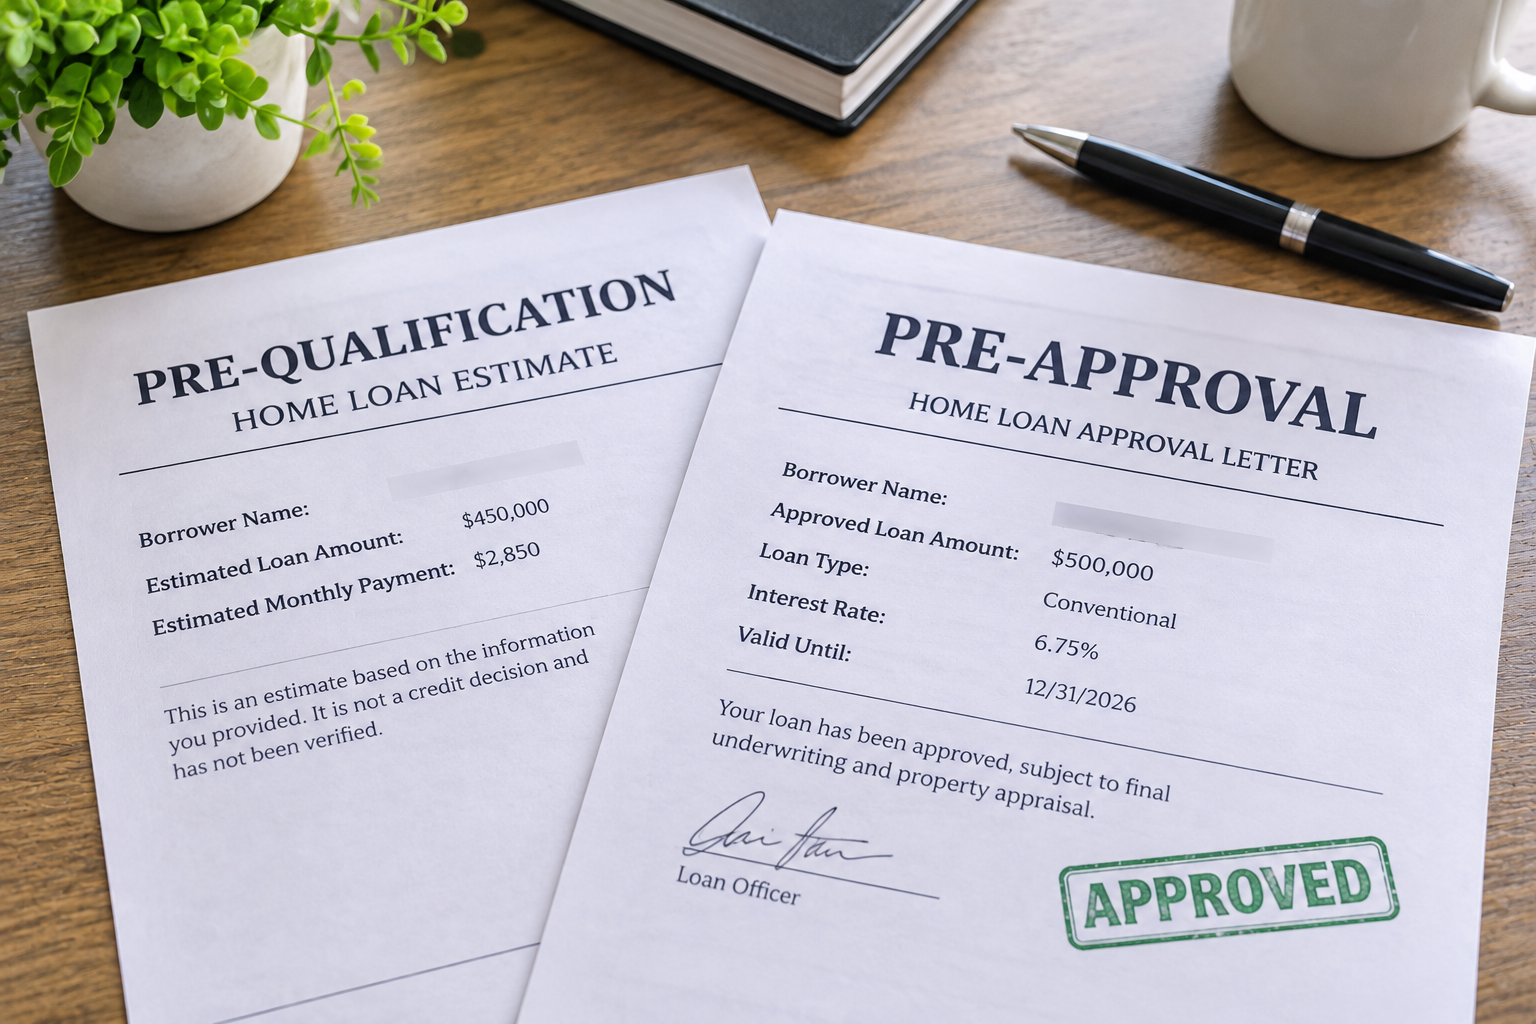
These two terms get mixed up a lot, and they aren’t the same.
Pre-qualification is usually a quick estimate based on information you share. It’s a helpful first look, but nothing is verified.
Pre-approval goes further. The lender reviews your documents and checks your credit, so the number is much more reliable.
If you’re serious about buying, a pre-approval is the one to get.
Why it matters
You’ll know your real budget. It’s easy to fall in love with a home that’s out of reach, and it’s just as easy to rule out ones you could afford. A pre-approval keeps your search realistic and focused.
Sellers take you more seriously. When a seller sees a pre-approval letter with an offer, they know you’re a qualified buyer. In a competitive market, that can make a real difference.
You can move quickly. Good homes in Lafayette, Moraga and Orinda often draw interest fast. With your financing already looked at, you can make a confident offer instead of scrambling.
It helps you avoid surprises. If something in your credit or paperwork needs attention, it’s far better to find out early, before you’re under contract.
What you’ll usually need
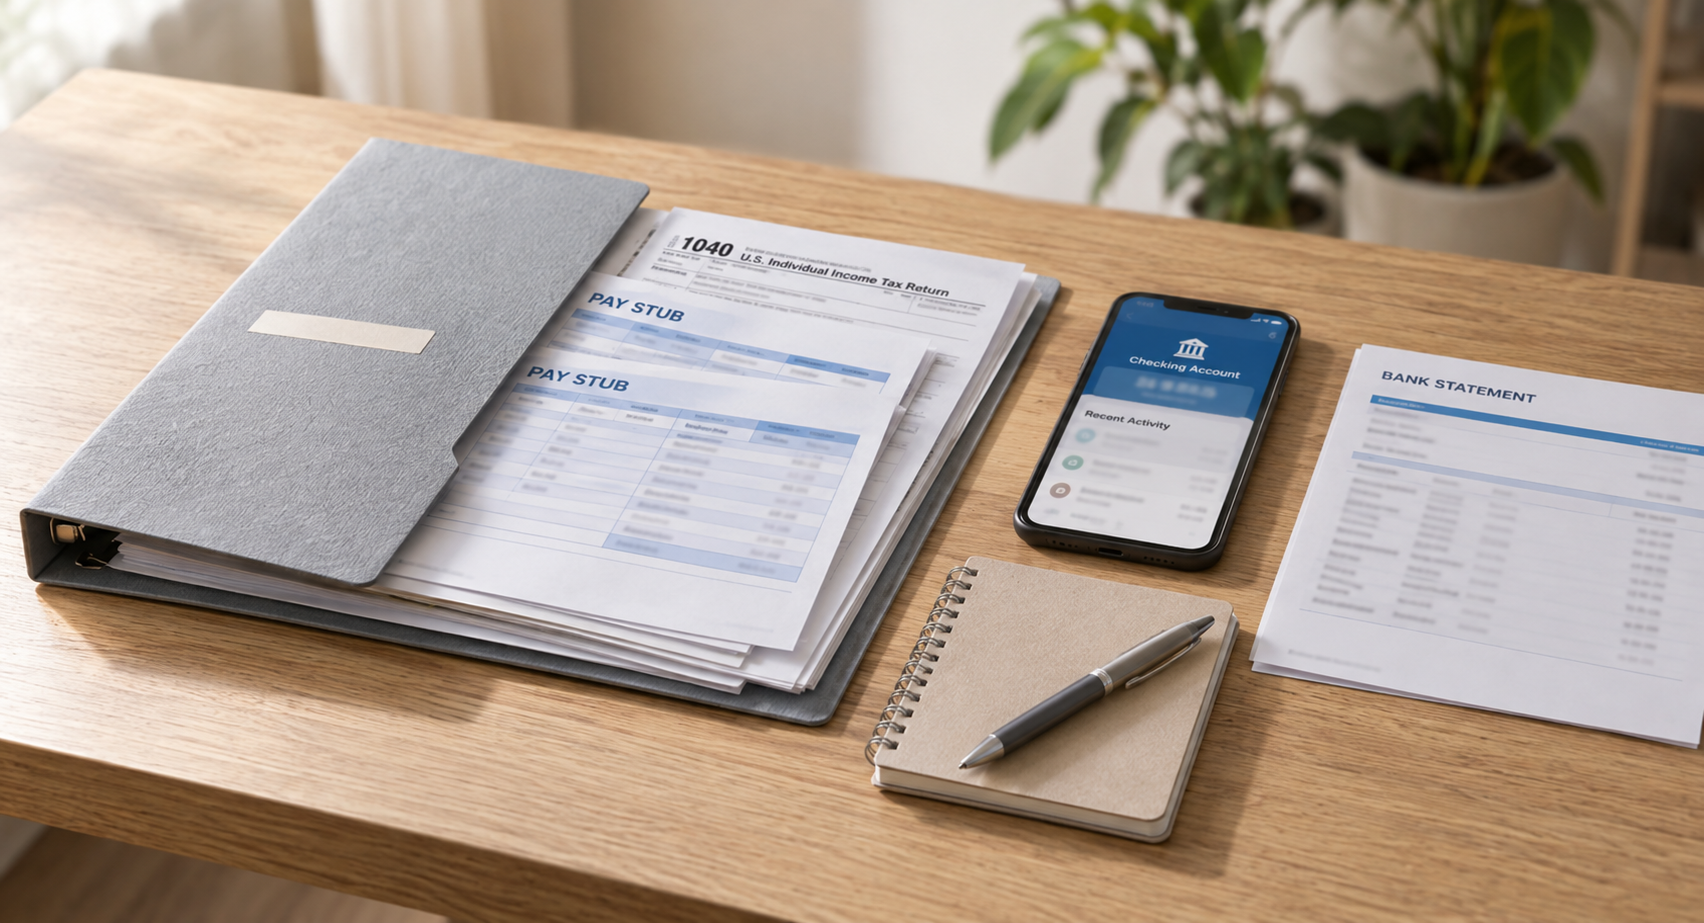
Every lender is a little different, but expect to share things like:
Recent pay stubs and W-2s (or other income documents)
Tax returns from recent years
Bank and savings statements
Details about your debts and monthly obligations
Permission for the lender to check your credit
If you’re self-employed, you’ll likely need a few extra documents, so it helps to start gathering them early.
How to get pre-approved
Talk to a lender. I’m happy to introduce you to trusted local lenders, and you’re always welcome to talk to more than one so you can compare.
Gather your documents. Having them ready makes the process quicker.
Review your options. Your lender can explain loan types, down payment choices and what they mean for your monthly costs.
Get your letter. Once approved, you’ll receive a pre-approval letter to include with your offers.
Credit inquiries from several mortgage lenders in a short period are often treated as one, but it’s worth asking your lender how it works for you.
A few things to keep in mind
A pre-approval is a strong starting point, but it isn’t a final loan commitment. Here’s what helps it stay solid:
Don’t make big purchases or open new credit before closing.
Don’t change jobs without talking to your lender first.
Keep your finances steady, including your savings and your bills.
Check the expiration date. Letters often last a couple of months, but it varies, so ask your lender.
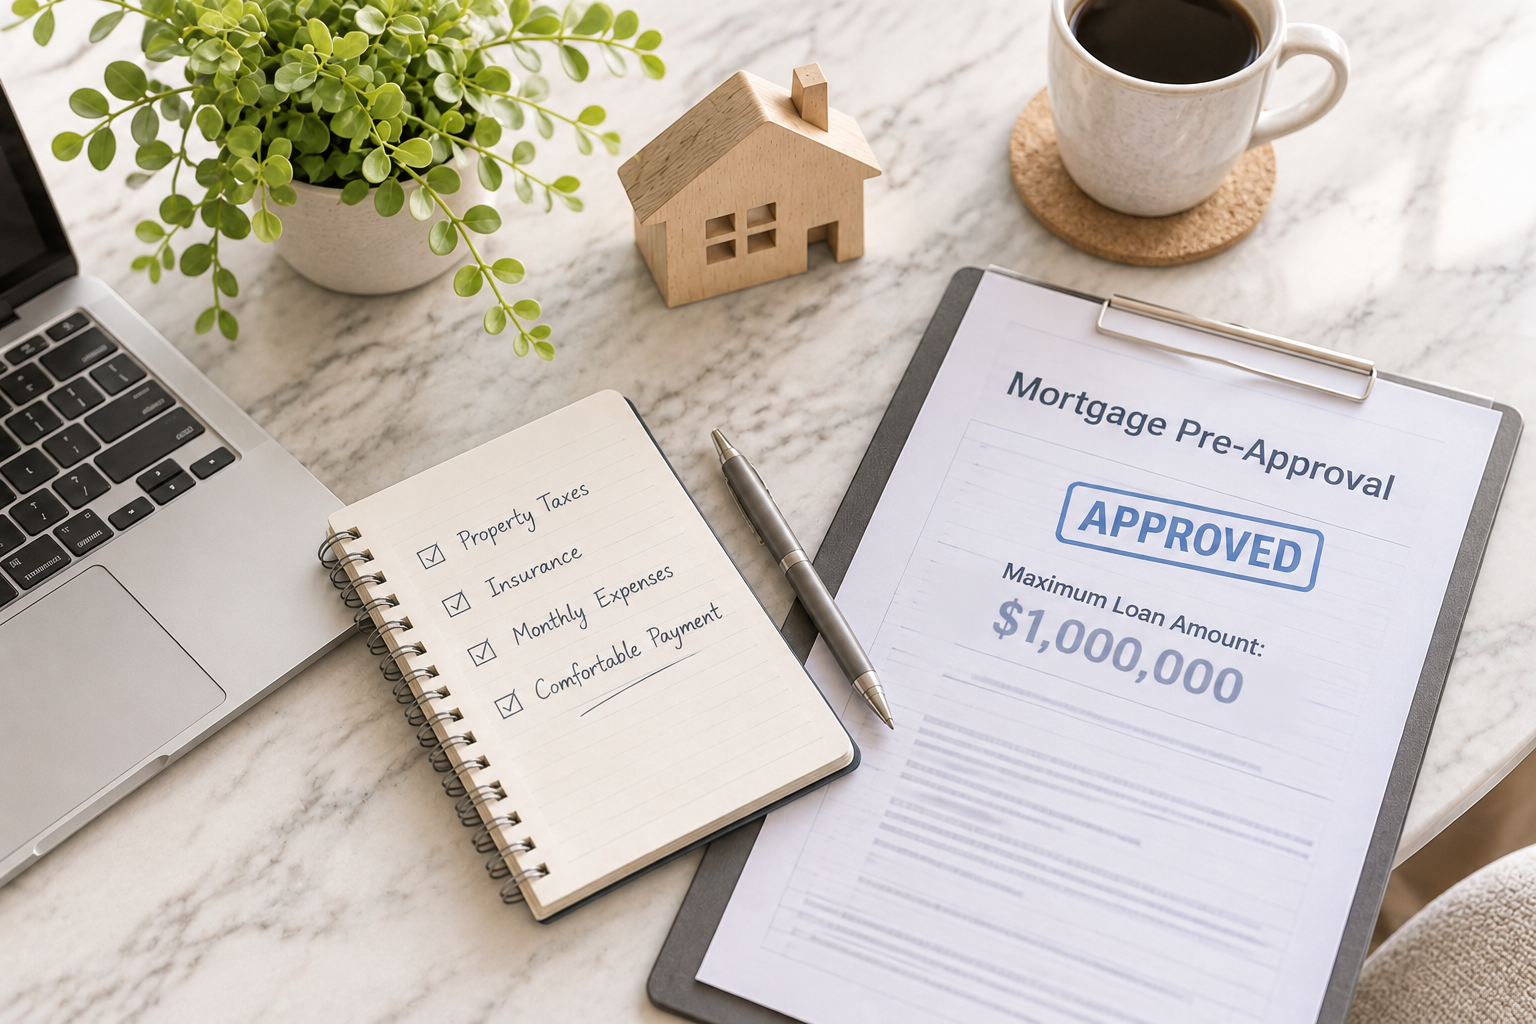
Your pre-approval is a starting point, not a ceiling
Just because you’re approved for an amount doesn’t mean you should spend all of it. I’ll help you think through what feels comfortable, including property taxes, insurance and day-to-day life, so you buy a home you can enjoy.
Let’s talk
Whether you’re a first-time buyer or moving within Lamorinda, I’d love to help you start on the right foot. Send me a message, say hi on Instagram or call anytime. No pressure, just a good conversation.
Talk soon,
Lynn
Lynn Molloy, REALTOR® | DRE 01910108 | Partner at The Beaubelle Group | Compass
(925) 818-7620 | lynn.molloy@compass.com